Germany's motorcycle market 2026: brands, models, Chinese manufacturers
Brands, models, dealer network – and when the Chinese brands will really arrive
Germany's motorcycle market is recovering from the Euro 5+ shock in 2026: BMW narrowly leads Honda and Kawasaki, while Chinese brands such as CFMoto and Voge are pushing ahead through the dealer network.
If you're looking at the statistics right now, you might be alarmed: 2025 was a terrible year on paper. But the story isn't that simple. Let's take a proper look at the market – without panic, but with the right figures. You can always find the latest figures in our market statistics at nbnl.de/statistik, which we update monthly based on the official KBA data.
The long view: smaller, but stable
Over 25 years, the market for motorcycles over 125 cm³ in Germany has shrunk, from around 170,000 new registrations in 2000 to approximately 96,000 in 2025. That is a decline of roughly 44 %. It sounds dramatic, but it is primarily a gradual structural change – not a crisis.
More important than the long-term curve is the fluctuation of the past two years, and that has a technical reason: the change from the Euro 5 emissions standard to Euro 5+ on 1 January 2025. At the end of 2024, dealers cleared out their Euro 5 stock with heavy discounts and one-day registrations, and many buyers snapped them up in November and December. The result: an artificially inflated record year in 2024 (around 247,000 powered two-wheelers) and a corresponding hangover in 2025 (around 159,000). The slump looks severe, but is largely a statistical counter-movement.
And 2026? Things are picking up again. In the first four months, more than 44,000 machines over 125 cm³ were newly registered – around a quarter more than in the same period last year. A motorcycle spring unlike any seen for a long time.
The brands: BMW ahead, but its lead is shrinking
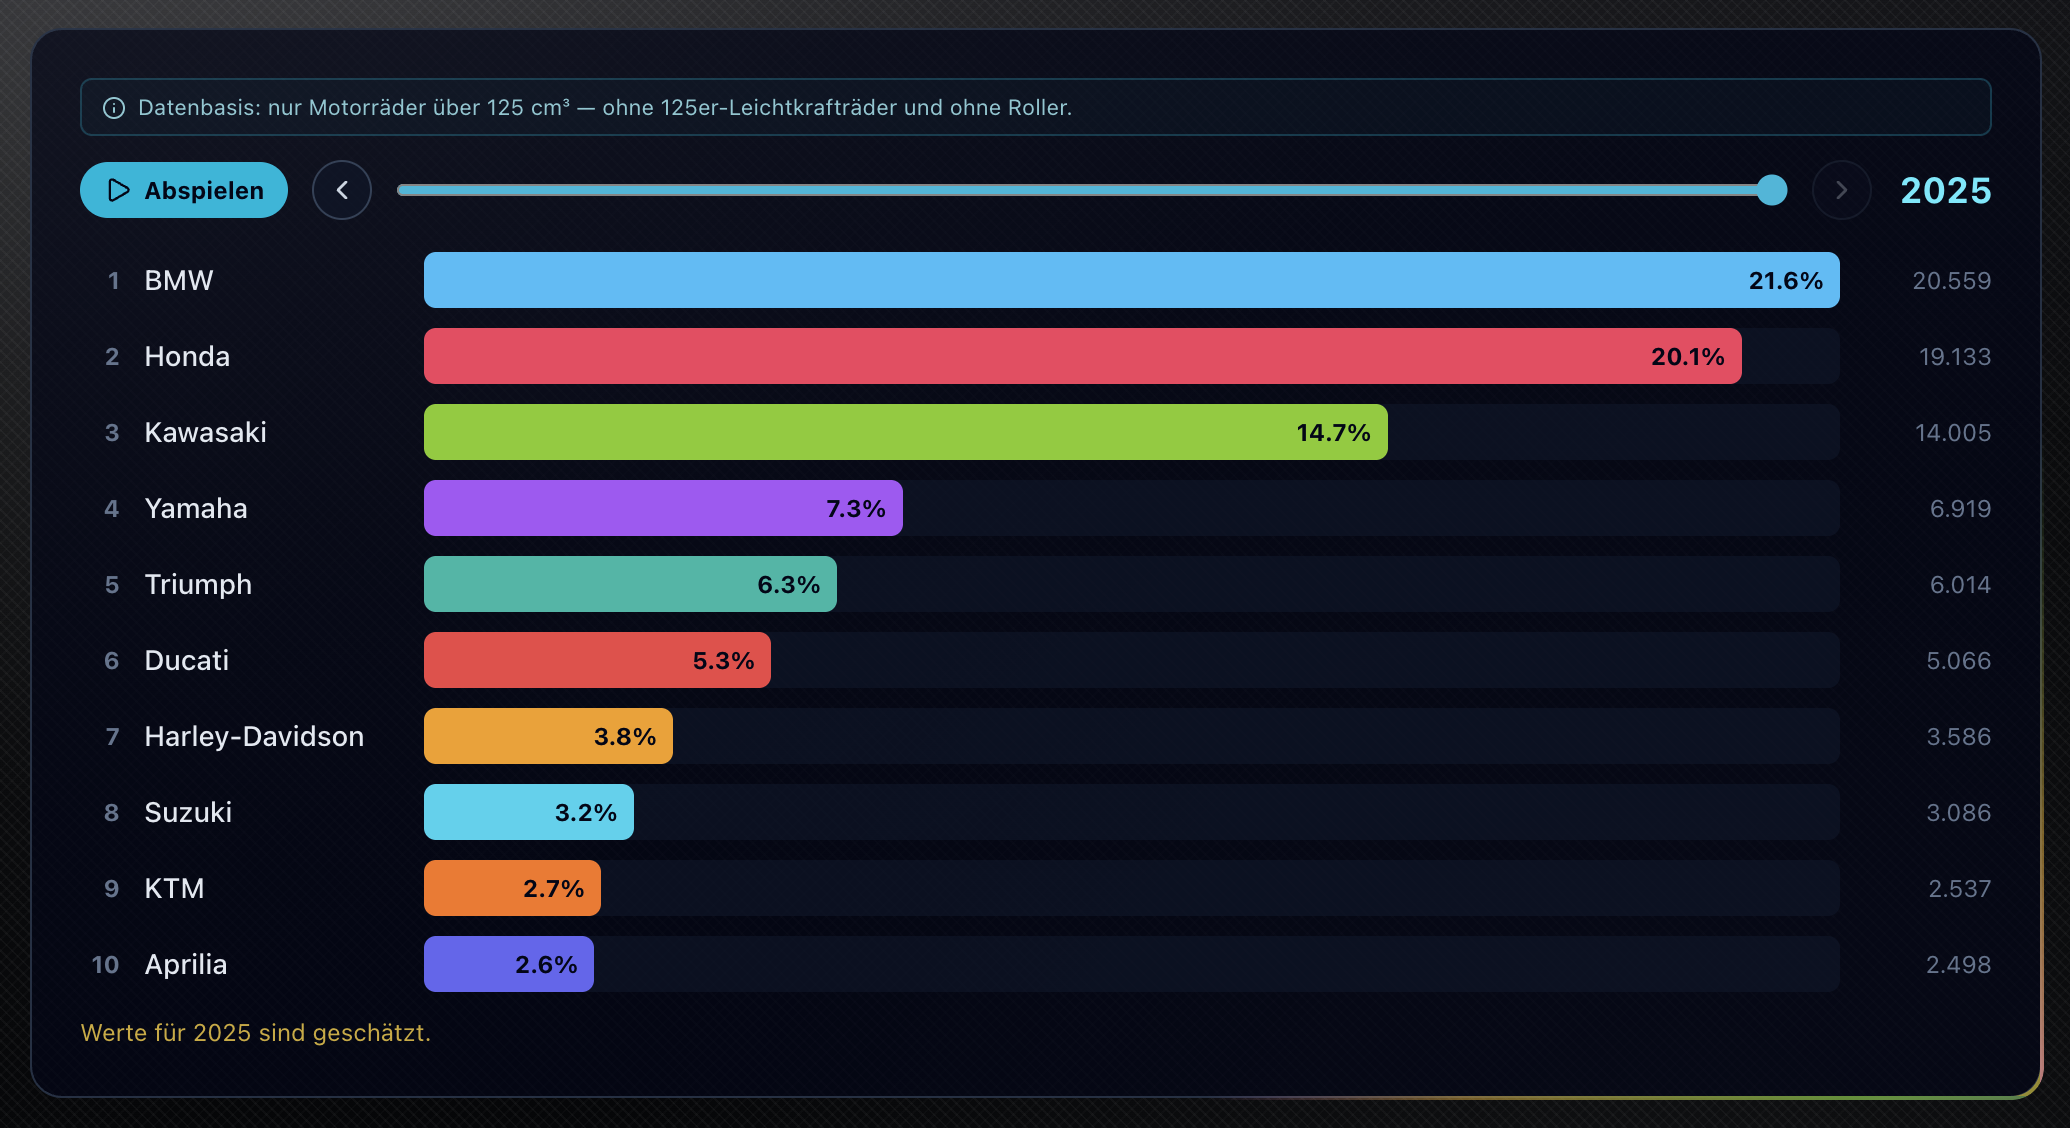
At the top, everything remains the same – and yet it is moving. BMW remains market leader, but with just over 21–22 % market share, it is now only narrowly ahead of Honda (around 20 %). Kawasaki follows in third place at approximately 15 %, with the rest distributed in single-digit figures.
KTM suffered the biggest collapse in 2025: financial difficulties plus the Euro 5+ effect resulted in a decline of around 80 % in Germany, to only approximately 2,700 machines. So if you think the market is static – no, there are genuine shifts in the balance of power right now.
The models: The GS reigns, naked bikes are back
Among the models, the BMW R 1300 GS has led virtually uninterrupted for years – GS dominance stretches far back through its predecessors, the R 1200 GS and R 1250 GS. Behind it, in positions 2 to 8, are primarily price-conscious Japanese all-rounders.
Excitingly, naked bikes are once again the most popular category for the first time in years. The Kawasaki Z 900 is a perennial favourite, joined by the smaller Z 650 and the fully-faired Ninja 650. And – this is the real headline – in 2025, models from China and India made it into the Top 50 for the first time: the Voge DS 900 X as an affordable adventure bike and the Royal Enfield Himalayan 450. In 2026, the CFMoto 450 MT has even made its way into the leading group of best-selling models.
The dealer network: This is where you see the future first
Now for the crucial question – and it is exactly the right one: you see the Chinese brands in the dealer network before you see them in the sales figures. That is precisely the pattern.
A brand does not sell first and build the network afterwards. It works the other way round: first win over dealers, train workshops, establish spare parts supply and warranties – and only once that is in place do the volumes come. The dealer network is therefore the leading indicator. And this is where the decisive developments are happening in 2026: established dealers are now adding CFMoto and Voge to their range. Where there were only Honda or Yamaha signs yesterday, there is now a Chinese bike in the showroom. Take a proper look at this in the "Dealer network" tab on the statistics page – that is where the trend becomes visible, long before it appears in the registration figures.
So when will the Chinese brands really arrive?
The honest answer: they are already here – just more quietly than the headlines suggest. They are only beginning to appear in Germany's pure sales figures, but the growth rates are brutal: in October 2025, CFMoto grew by around 118 %, while Voge even grew by more than 218 %. CFMoto has now pushed its way into the manufacturers' Top 10.
Why the hesitation nonetheless? The biggest sticking point is not the technology – that has long since matured – but resale value. Anyone buying a Chinese bike today saves money on the purchase, but is still venturing somewhat into the unknown with the brand. However, this trust grows with every year, every satisfied owner and every stable dealer network. This is exactly what has already happened with Hyundai and Kia in the car market.
Looking across the border: They have long been there in Spain
If you want to know where things are heading, look south. Germany is a few years behind when it comes to Chinese bikes – other European markets show what is coming.
In Spain, the pioneer, Zontes and Voge have already moved into the Top 4 brands, with Voge temporarily reaching around 8 % market share. QJMotor has entered the Top 10 for the first time. Spain is also the only one of the five major European markets to have grown at all in 2025.
France perhaps provides the most striking picture: over the first three quarters of 2025, CFMoto sold more motorcycles there than Ducati, KTM and Suzuki – with around 3.4 % market share and approximately 4,700 machines. A Chinese brand ahead of three traditional manufacturers. Voge and QJ Motor are also growing strongly.
Italy, Europe's largest market, shows the same pattern: Voge has advanced to 6th place, ahead of BMW, while CFMoto, QJ Motor and Zontes are all growing significantly.
The pattern is the same everywhere – affordable prices, now solid technology, a growing dealer network. Germany is no exception, merely a late starter.
Conclusion
My impression: the 2025 slump is only half as bad as it looks; it was largely the Euro 5+ hangover. More exciting is what is happening underneath – the old dominant players are still leading, but the Chinese brands are pushing up from below with all their might. And if you want to know when they are really here, it is best not to look at the sales charts, but at the dealer network. That is where the future is decided first. Keep following the figures – the latest values are always available in our market statistics, updated monthly using official KBA data.